By Blossom Ukoha
“My trajectory [was] an accumulation of different chapters across finance, risk, human capital, and corporate management.”
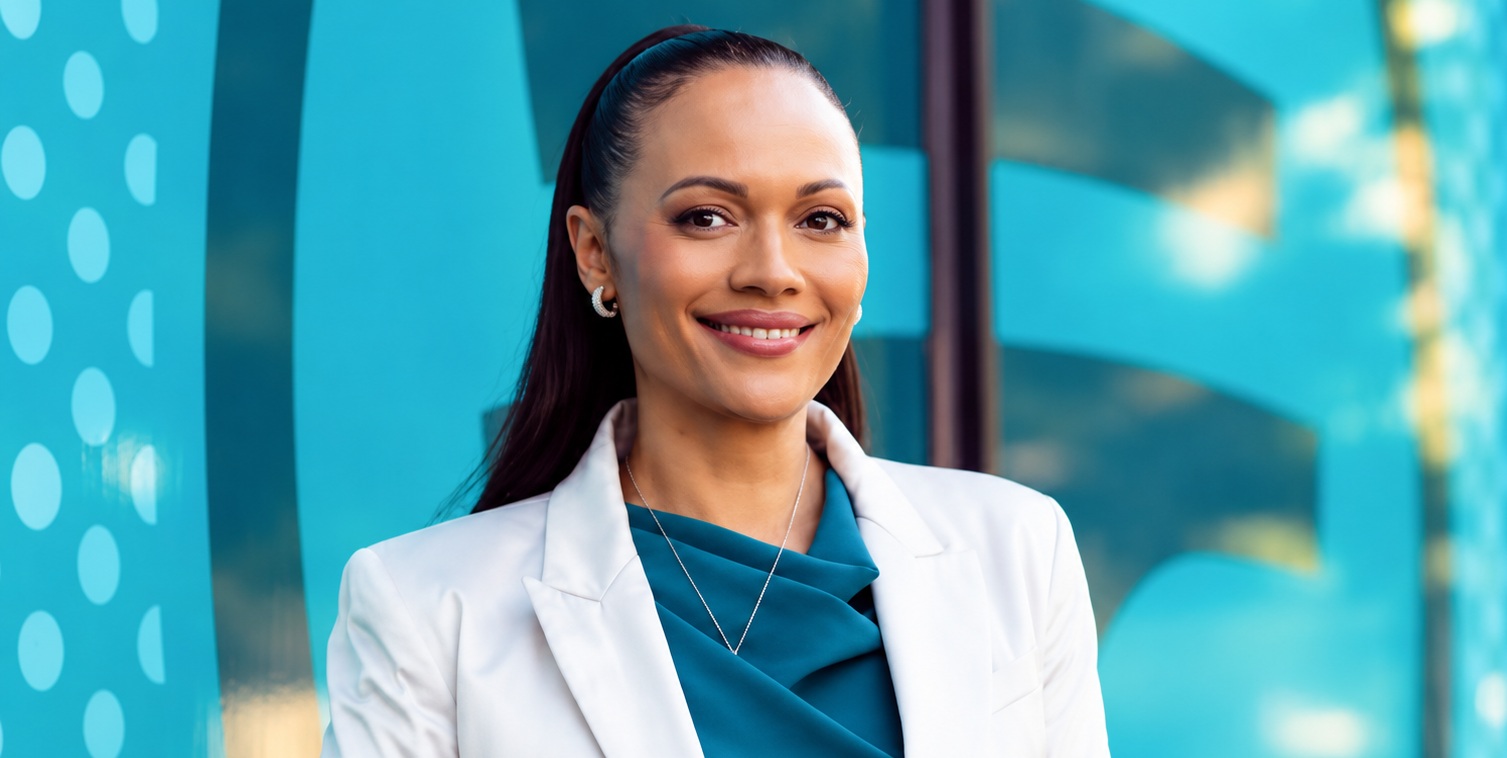
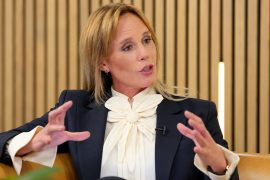
For Lytania Johnson, becoming Chief Executive Officer of First National Bank (FNB) was not the result of a single career-defining move. It was the culmination of more than 25 years of experience, built across different functions and responsibilities within FNB and FirstRand. Her journey illustrates how breadth of experience, continuous learning and the willingness to embrace unexpected opportunities can prepare women for the highest levels of leadership.
Johnson became CEO of FNB and of the newly configured Retail and Business Banking (RBB) segment on 1 April 2026, succeeding Harry Kellan. The new structure brings retail and business banking closer together, with a focus on households, entrepreneurs and small businesses.
The scale of the appointment is significant. FNB traces its roots to 1838 and is FirstRand’s largest franchise. In the year ended June 2026, FNB reported normalised earnings of R26.4 billion, up 12%, while return on equity was approximately 40%. Customer deposits exceeded R1 trillion, and FNB contributed about 59% of FirstRand’s earnings.
Johnson is therefore taking charge of one of the group’s most consequential businesses at a time when banking is increasingly shaped by digital transformation, changing customer expectations and the need to broaden economic participation.
From Finance to the CEO’s Office
Johnson’s career did not follow a straight line.
She joined FNB in 2001 in the finance division of FNB Credit Card before moving into risk management. In 2015, she became CEO of FNB’s eWallet business, giving her experience in a rapidly developing area of financial inclusion and digital payments.
In 2016, she became Chief Ethics Officer for the FirstRand Group, followed by her appointment as Chief Risk Officer of FNB in 2017. In January 2023, she became CEO of FNB’s Personal Segment, taking direct responsibility for a major customer-facing business.
Her qualifications include a BCom in Management Accounting, risk-management qualifications and leadership training through Wits Business School.
The progression is notable because Johnson did not remain within one specialist function. She moved through finance, risk, ethics, digital banking, personal banking and corporate leadership.
That breadth ultimately became part of her preparation for the CEO role.
Turning Detours Into Leadership Capital
Johnson has previously spoken about accepting roles that others might have interpreted as a step backwards.
Rather than seeing such moves as setbacks, she viewed them as opportunities to acquire experience that would become valuable later.
Her leadership philosophy is grounded in three principles: lead with humility but confidence, enable others to succeed, and continue learning and adapting.
That approach is particularly relevant in banking, where today’s CEO must understand far more than financial performance. Risk, technology, regulation, customer behaviour, people, capital allocation and innovation are all interconnected.
Johnson’s career has given her exposure to many of these areas.
Her experience leading eWallet was particularly important because it connected financial services with broader questions of access and participation. That perspective continues to influence how she approaches FNB.
Leading a Bank Built Around Participation
Johnson’s new RBB structure brings retail and business banking together around a common customer ecosystem.
Explaining the rationale, she said:
“FNB has so many leading customer propositions built on the back of a strong culture of innovation and the promise of help. This simplified structure will accelerate the bank’s ability to serve its customers better.”
She added that bringing the two businesses together would help FNB better serve “entrepreneurs, small businesses and households who require solutions that can cover their personal and business needs.”
The numbers demonstrate the scale of that ecosystem.
According to Business Day, FNB ended the June 2026 financial year with almost nine million retail customers, while digitally active customers reached 8.16 million. FNB app transaction volumes increased 10% to 782 million, while activated virtual cards reached 6.3 million.
The bank’s community-economy business also recorded significant growth. Advances to small and medium-sized businesses with annual turnover below R5 million increased by 31%, while community-economy revenue grew 14% to R4.2 billion. FNB had more than 250,000 active business customers in this segment.
For Johnson, these figures represent more than banking transactions. They are part of what she calls a “participation ecosystem.”
“What is important for us is to deliver solutions that allow our customers to grow with us and provide solutions that facilitate participation beyond banking,” she has said.
The philosophy places the bank’s role within a broader economic context: helping households, entrepreneurs and small businesses access financial tools that can support growth.
A Woman Leading a Meaningful Portfolio
Johnson’s appointment also contributes to an important development within FirstRand.
But Johnson has argued that representation should go beyond having women present at senior tables.
“What we need to do more of, and be very intentional about, is that they are leading meaningful portfolios… truly the owners of income statements,” she has said.
That distinction is central to her leadership story.
For Johnson, women’s advancement cannot be measured only by the number of women holding executive titles. It must also be measured by whether women are being entrusted with revenue, strategy, risk, customers and business performance.
She has expressed the hope that the next generation will eventually view women leading major businesses not as exceptional because of their gender, but simply as talented individuals occupying important leadership positions.
Leadership Beyond Gender
Johnson also views diversity as broader than gender.
She has highlighted the importance of diversity of background, age and skill sets, arguing that different perspectives can improve how organisations understand their customers.
At FNB, this has included practical efforts to bring behavioural expertise into understanding customer needs.
The philosophy reflects a leader who sees innovation not simply as a technology issue, but as an organisational capacity to understand people and adapt to how they live, work and transact.
After 25 years inside FirstRand, Johnson combines deep institutional knowledge with an emphasis on continuous adaptation.
The CEO Does Not Own the Capital
Johnson’s rise also highlights an important distinction in corporate power.
Becoming CEO gives her substantial operational and strategic authority. She is responsible for leading FNB’s strategy, performance, customers and people and for working within FirstRand’s broader governance and capital framework.
But executive leadership does not automatically mean ownership of the capital behind the business.
FirstRand’s 2025 annual financial statements show that the Public Investment Corporation held approximately 15.7% of the parent company, while BEE partners held 4.9%. BlackRock held approximately 3.0%, and Old Mutual held 2.7%.
The ownership structure therefore remains distributed among institutional, BEE, corporate and other shareholders.
Johnson’s position illustrates an important distinction: she exercises significant executive power without personally controlling the majority of the company’s underlying capital.
That distinction matters in the broader conversation about women’s economic power.
Women are increasingly moving into positions where they make major commercial decisions. But leadership at the executive level is only one dimension of economic influence. Ownership of shares, investment capital, businesses and assets represents another.
What Her Journey Reveals
Lytania Johnson’s rise from FNB’s finance division in 2001 to CEO in 2026 demonstrates the value of a sustained leadership pipeline.
Her career was built across different chapters finance, risk, ethics, digital banking, personal banking and executive leadership.
Each chapter added another layer of experience.
Her story therefore challenges the idea that leadership must follow a perfectly predictable path. Sometimes, the roles that appear to be detours become the experiences that prepare a person for a much larger responsibility.
More importantly, her appointment puts a woman at the helm of a banking franchise that serves millions of customers and plays a significant role in South Africa’s economy.
The significance is not simply that a woman became CEO.
It is that a woman with more than two decades of institutional experience is now leading a major business, responsible for its strategy, performance and future direction.
And Johnson’s own message to women in leadership is perhaps the clearest indication of what she believes comes next: women should not simply be invited to the table.
They should be trusted with meaningful portfolios, meaningful responsibility and the opportunity to lead.


Comments are closed.