By Blossom Ukoha
51% of US small employer firms identified uneven cash flow as a financial challenge, according to the Federal Reserve’s 2025 Small Business Credit Survey. The finding highlights a problem many entrepreneurs overlook: a business can be profitable on paper and still struggle to pay its bills.
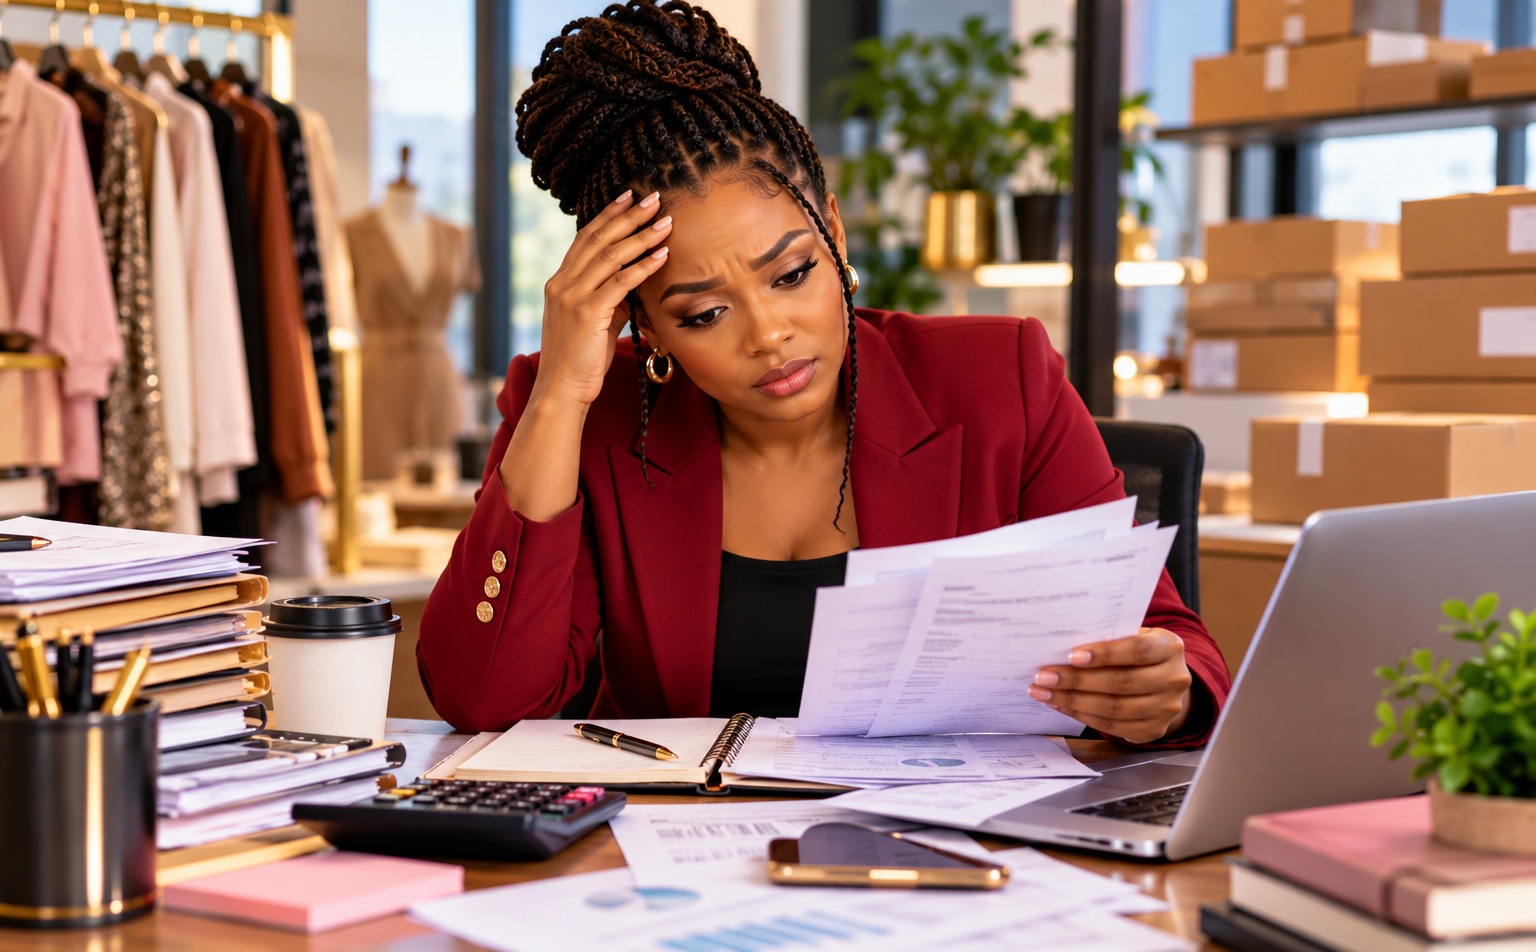
Imagine a woman who has just secured a major business contract. Sales are growing, customers are placing orders, and her financial statements show a healthy profit. She hires additional staff, purchases more inventory and prepares to expand.
Then the bills arrive.
Her employees need salaries. Suppliers expect payment. Rent is due. But her biggest customer has not paid the outstanding invoice.
Suddenly, a business that appears successful is struggling to keep its doors open.
This is the cash flow trap, and understanding it is essential for every entrepreneur who wants to build a sustainable business.
When Profit Does Not Mean Money in the Bank
Profit and cash flow are not the same thing. Profit measures what remains after accounting for revenue and expenses over a given period. Cash flow tracks the actual movement of money into and out of a business.
Consider a company that completes a ₦10 million contract and records a profit of ₦2 million. If the customer will not pay for another 60 days, that profit does not automatically provide money for today’s salaries, supplier invoices or operating expenses.
The business may be profitable, but it cannot spend money it has not received.
For entrepreneurs, especially women managing growing businesses alongside other responsibilities, this distinction matters. Strong sales can create confidence, but without enough available cash, even a promising business can face serious financial pressure.
The question is not only how much your business earns, but when that money becomes available to use.
Five Reasons Profitable Businesses Run Out of Cash
1. Customers Pay Too Slowly
A business may deliver its products or complete a service promptly, only to wait weeks or months for payment. Meanwhile, its own financial obligations continue.
This is particularly challenging for businesses working with corporate clients or customers who purchase on credit.
Entrepreneurs can reduce the pressure by issuing invoices promptly, establishing clear payment terms and following up on overdue accounts. Where possible, requesting deposits or milestone payments can help cover costs before a project is completed.
2. Growth Consumes More Cash Than Expected
Winning a major contract sounds like good news, but fulfilling it may require significant spending before payment arrives.
Hiring workers, purchasing materials, increasing production and paying for transportation can drain available cash.
Before accepting a large order, calculate the cost of fulfilling it and determine whether the business can cover those expenses while waiting for payment. Growth should strengthen the business, not leave it unable to meet existing commitments.
3. Too Much Money Is Tied Up in Inventory
Products sitting unsold on shelves represent money that has already left the business but has not returned through sales.
Buying in bulk may reduce the cost per unit, but excessive inventory can leave insufficient cash for salaries, rent and other essentials.
Monitor which products sell quickly, which remain unsold and how often stock needs replenishing. Let actual demand guide purchasing decisions rather than optimism alone.
4. Operating Costs Keep Rising
Rent, salaries, electricity, transportation and subscriptions can gradually consume available cash. These expenses often remain due even when sales decline or customers delay payment.
Regularly reviewing expenditure helps business owners identify unnecessary costs, negotiate better terms and prioritise essential spending.
5. Owners Withdraw Too Much Money
Entrepreneurs deserve to benefit from their hard work. However, withdrawing money without considering upcoming obligations can weaken a business.
A healthy bank balance does not necessarily mean all the money is available for personal spending. Some may already be needed for taxes, supplier payments, salaries or debt repayments.
Establishing a consistent owner salary or withdrawal policy helps protect the company’s working capital while allowing the founder to earn from the business.
How to Escape the Cash Flow Trap
Managing cash flow does not require complicated financial systems. It requires consistent attention to the timing of money.
Start by preparing a weekly cash flow forecast. Record expected income, upcoming expenses and the balance likely to remain. A rolling 13-week forecast can help identify potential shortages before they become emergencies.
Next, monitor outstanding invoices and follow up before payments become overdue. Review inventory regularly, plan major purchases carefully and negotiate payment terms that align more closely with customer collection schedules.
Build a cash reserve gradually, too. Even a modest buffer can provide breathing room when payments are delayed or unexpected expenses arise.
Finally, separate business finances from personal spending and avoid making major financial decisions based solely on the current bank balance.
Profit Is Good. Cash Keeps You Operating.
A profitable business has demonstrated its ability to generate earnings. A financially resilient business must also be able to meet its obligations when they fall due.
That means looking beyond sales figures to understand how quickly customers pay, how much money is tied up in inventory, when bills become due and how much cash remains available.
For every entrepreneur building a business, the lesson is clear: do not confuse a successful sales month with financial security.
Growth matters. Profitability matters. But cash flow management determines whether a business can pay its people, fulfil its promises and remain operational long enough to grow.
The goal is not simply to build a business that looks successful on paper. It is to build one that can survive, expand and create lasting value.
What is the biggest cash flow challenge your business faces: late payments, rising costs, inventory or unpredictable sales? Share your experience and help other entrepreneurs learn from it.


Comments are closed.